




Simplified taxation system for law firms: what you should know
Ukraine has two main systems of taxation of legal entities: general (income tax and VAT payers or those without) and simplified (single tax payers with or without VAT). The latter is usually the most suitable for a law firm.
When submitting documents for the registration of a legal entity, a law firm may indicate in the application for state registration of a legal entity (Form No. 2) on the additional page 9, information on the choice of the simplified taxation system (single tax group 3, select the tax rate in %), indicate the place of business, and determine the desired date of voluntary registration as a value added tax payer (until the sales volume reaches UAH 1 million). The procedure for selecting and applying the simplified taxation system with the payment of a single tax is set forth in Section XIV «Special Tax Regimes» of the Tax Code of Ukraine.
If, when submitting documents for state registration, a banking institution fails to indicate the choice of the simplified taxation system, such banking institution will be registered as a taxpayer under general conditions (income tax payer). Subsequently, in order to choose the simplified taxation system, an application should be submitted in the form approved by the Order of the Ministry of Finance of Ukraine dated 16.07.2019 No. 308.
According to the second paragraph of subpara. 298.1.2 of the Tax Code, business entities registered in accordance with the procedure established by law (newly established), which within 10 days from the date of state registration have submitted an application for the simplified taxation system and the single tax rate established for the third group, which does not provide for the payment of value added tax, are considered single tax payers from the date of their state registration. The transition to the simplified taxation system with the choice of the single tax rate may be made at the beginning of any quarter, but only once a year.
In view of the current version of Article 293 of the Tax Code, a law firm may be a single tax payer of the third group only. The following rates are set for the third group of single tax payers:
- 3% of income - if VAT is paid on a general basis;
- 5% of income - if value added tax is included in the single tax (more convenient and easier to understand).
The reporting period for single tax payers of the third group is a calendar quarter.
The reporting deadline is 40 calendar days after the end of the reporting quarter.
The deadline for paying the single tax is within 50 calendar days after the end of the reporting quarter.
By the way, December 15, 2023 is the last day to apply for the simplified taxation system starting from the first quarter of 2024.
The article was prepared by Dmytro Khutornyi, Deputy Chairman of the UNBA Committee on Legal Practice.
Popular news
Legislation
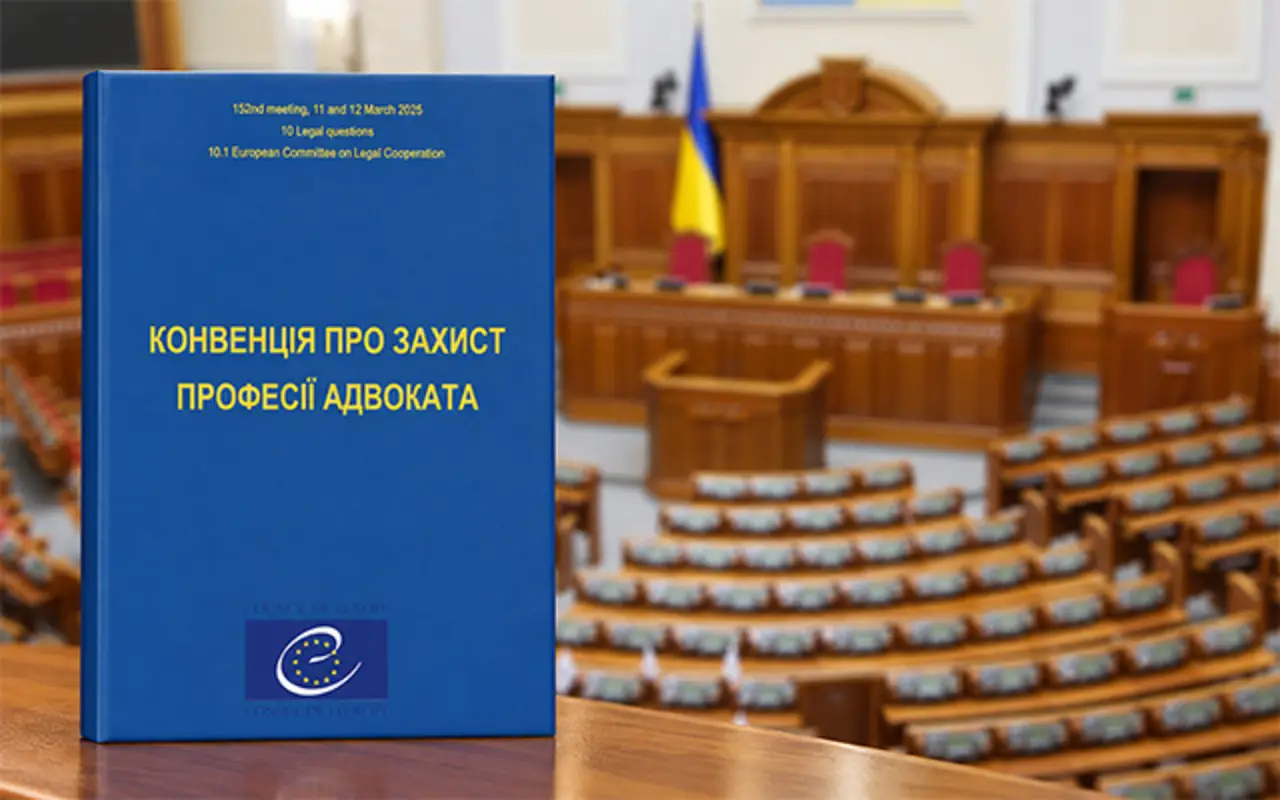
A bill implementing the Convention on the Protection of the Professions of Lawyer has been introduced
The constitutional guarantees of legal aid, defense, and the independence of advocacy cannot be realized without protecting advocates from unwarranted interference in their professional activities, including searches, the seizure of professional materials and the use of criminal procedural mechanisms to exert pressure.
Abroad
The CCBE is discussing European justice and issues related to the protection of advocates
Today, October 2, a meeting of the Standing Committee of the Council of Bars and Law Societies of Europe (CCBE) is taking place in Brussels. On the agenda are the protection of the advocate profession, the rule of law, attorney-client privilege, and changes in the European justice system.
Rule of Law Roadmap
The UNBA presented the key provisions of the future law on advocacy in Brussels
The Ukrainian National Bar Association presented its proposals for the upcoming law on advocacy, aligned with the Rule of Law Roadmap. The presentation covered topics such as access to the profession, self-governance, disciplinary procedures, professional development and guarantees for the practice of advocacy.
Educational events
Advocates were taught to voice their complaints without making accusations
In a difficult conversation, it’s easy to confuse facts with opinions, feelings with accusations, and requests with demands. How can you express dissatisfaction, explain your own needs, and propose a specific solution while still allowing your conversation partner the opportunity to refuse or suggest an alternative?
Guarantees of the practice of law
Unrestricted access to advocates' accounts poses a risk of client data disclosure — BCU
Information regarding transactions in the bank accounts of an advocate, a law firm, or a bar association from which clients can be identified, as well as the fact and subject matter of a request for legal assistance, the purpose of payments, and the amount of the fee constitutes attorney-client privilege. This rule applies regardless of whether the information also constitutes banking information and is in the possession of a bank.
Guarantees of the practice of law
The contract provides for a video conference, but the court requires in-person appearance: how should an advocate proceed?
Many advocates today work remotely; therefore, their agreements with clients provide for the provision of legal assistance via videoconferencing. However, this form of work does not, in and of itself, create an unconditional obligation for the court to conduct every hearing via videoconference.
Guarantees of the practice of law
Independent oversight is necessary before using CISA materials against an advocate – Lidiya Izovitova
Before the prosecution uses information obtained during covert investigative actions and related to an advocate’s activities, independent procedural oversight must be conducted. It is necessary to determine whether such information is covered by attorney-client privilege and whether it may be disclosed.
Legislation
Handing over a bank card should not automatically constitute a crime – UNBA
Criminal liability for transferring a bank card or access to an account should arise only if it is proven that the person knew the card or account would be used as a means to commit an intentional crime. The mere fact that a payment instrument was transferred or that an account was used by a third party is not sufficient.
Publications
Vasyl Kolishnyi, «Law and Business» Supporting mental health should become part of the professional culture of the Bar, - H. Udovenko

Volodymyr Matsko Extradition during wartime: when the risks outweigh the request

Volodymyr Matsko Extradition as a systemic form of rights violations

Victoria Yakusha, Law and Business The anti-corruption vertical cannot «take care» of the Bar as an institution, - acting head of the HQDCB

Censor.net Protecting advocates – protecting justice: addressing concerns about the new law

Ihor Kolesnykov A BRIEF SUMMARY REGARDING THE APPLICATION OF THE ORDER ON EXTENDED CONFISCATION IN LATVIA REGARDING FINANCIAL ASSETS OF…

Valentyn Gvozdiy WORKING IN A WAR ZONE

Lydia Izovitova Formula of perfection

